DDTL 1.0 signed
$2.3B SOFR + 8.75% = 14.05%*
CoreWeave Compute Acquisition Co. II borrows against GPUs and two customer contracts. CoreWeave, Inc. guarantees full payment and pledges the borrower’s equity.
CoreWeave owed $35.6 billion of principal at June 30, 2026. Its GPU loans, DDTLs (delayed-draw term loans), sit in separate borrowers that own the GPUs and the customer contracts. Its bonds sit at the parent. We read the filings to map who owes what, and what each lender has recourse to.
Not advice. This is a research summary of CoreWeave's public filings. It is not investment, credit or legal advice, a credit rating, or an offer or solicitation to buy or sell any security. We summarize agreement terms, and some terms are redacted or unfiled. Read the filed documents before relying on any term. Figures marked as our estimate are our calculations, not company disclosures.
Every loan, note, convert and amendment in CoreWeave's filings, by signing date and rate at signing. The last step shows the bridge to what was owed at June 30, 2026.
| Signed or issued to date | $51.18B |
| Signed after June 30 (DDTL 5.5, 2033 converts) | −$6.80B |
| Revolver, undrawn | −$2.50B |
| DDTL 4.0 and 5.0, undrawn | −$7.66B |
| DDTL 1.0, 2.0 and 3.0, repaid or never drawn | −$3.96B |
| OEM, software and Magnetar | +$5.29B |
| Owed at June 30, 2026 | $35.55B |
| Jul 30, 2023 | GPU loans | DDTL 1.0 signed at SOFR + 8.75%, with the parent guarantee and pledge ($2.30B) |
| Nov 8, 2023 | Amendments | DDTL 1.0 parent guarantee First Amendment adds buyback baskets, including a $40M buyback |
| May 16, 2024 | Amendments | DDTL 1.0 First Amendment raises the margin from 8.75% to 9.6196%. It cuts the liquidity requirement to the greater of $18.75M and 4.0%, capped at $56.25M, and extends the cure window to 30 days. Guarantee second amendment the same day |
| May 16, 2024 | GPU loans | DDTL 2.0 signed at $5.66B with room for $1.84B more; the First Amendment added $100M, for up to $7.6B ($5.66B) |
| Jun 21, 2024 | Parent debt | Revolving credit facility signed at $100M, with JPMorgan as the only lender, at SOFR + 1.75% ($100M) |
| Aug 29, 2024 | Amendments | DDTL 2.0 First Amendment adds $100M of commitments, for up to $7.6B, and sets the minimum draw at $6.1B ($100M) |
| Oct 7, 2024 | Parent debt | Revolver Amendment No. 1: $100M to $650M, $500M secured and $150M unsecured; ten more banks join ($650M) |
| Dec 2, 2024 | Parent debt | Revolver Amendment No. 2: all $650M of commitments become secured |
| Dec 31, 2024 | Amendments | DDTL 2.0 Limited Waiver and Second Amendment: lenders waive defaults from five draws that overstated the borrowing base. The borrower may now own subsidiaries, and CoreWeave entities in Spain, the U.K. and Sweden become obligors |
| Feb 28, 2025 | Amendments | DDTL 2.0 Third Amendment sets end dates for the foreign entities’ interim obligor status and a June 13, 2025 perfection deadline; post-closing items sit on an unfiled schedule |
| May 2, 2025 | Parent debt | Revolver Amendment No. 3: $650M to $1.5B, maturity May 2028, with a springing maturity of December 30, 2026 ($1.50B) |
| May 27, 2025 | Parent debt | 9.250% senior notes due 2030; only CoreWeave Cash Management signed as guarantor ($2.00B) |
| Jun 6, 2025 | Amendments | DDTL 2.0 Fourth Amendment extends the draw period to September 29, 2025 |
| Jul 25, 2025 | Parent debt | 9.000% notes due 2031 ($1.75B) |
| Jul 28, 2025 | GPU loans | DDTL 3.0 signed at SOFR + 4.00%: two borrowers, guarantee covers one ($2.60B) |
| Sep 29, 2025 | GPU loans | Fifth Amendment to DDTL 2.0 adds the 2.1 tranche at SOFR + 4.25%, with its own collateral pool, waterfall and covenants, and a $2.4B minimum draw ($3.00B) |
| Nov 5, 2025 | Amendments | Parent guarantees for DDTL 1.0 and 2.0 amended to permit payments on a separate convertible promissory note, capped at $225M. It is not one of the 2031 converts |
| Nov 10, 2025 | Parent debt | Revolver Amendment No. 4: $2.5B, maturity November 2029, margin unchanged at 1.75%. Debt Holdco I and Weights and Biases join as guarantors, and the GPU borrowers become restricted subsidiaries ($2.50B) |
| Nov 10, 2025 | Amendments | DDTL 1.0 Second Amendment to the credit agreement. A filed guarantee amendment references it; its terms are not filed |
| Dec 7, 2025 | Amendments | Parent guarantees for DDTL 1.0 and 2.0 amended to permit cash interest and conversion settlements on the 2031 converts, cash on redemption, repurchase or maturity after three years, and the capped call premiums |
| Dec 11, 2025 | Parent debt | 1.75% converts due 2031 ($2.59B) |
| Dec 31, 2025 | Amendments | DDTL 3.0 First Amendment: coverage test first applies October 31, 2027, six months later; contract test restarted February 2026; liquidity minimum reset to $100M until August 2027; unlimited equity cures until October 28, 2026; OpenAI order form restated and amended; Morgan Stanley and MUFG gain consent over material contract changes |
| Mar 30, 2026 | GPU loans | DDTL 4.0 signed with a bad-acts guarantee only: $4.04B fixed and $4.46B floating ($8.50B). On the same day, two Applied Digital leases move to the DDTL 4.0 borrower, backed by a parent springing guaranty (section 07) |
| Apr 14, 2026 | Parent debt | 9.750% notes due 2031 and 1.75% converts due 2032 ($5.75B) |
| Apr 21, 2026 | Parent debt | 9.750% notes due 2031, add-on ($1.00B) |
| May 15, 2026 | GPU loans | DDTL 5.0 signed at SOFR + 4.50%, with two customer contracts ($3.10B) |
| Jun 18, 2026 | Parent debt | 9.625% notes ($1.25B) and €2.0B 8.500% notes due 2032, the euro notes at the 10-Q’s $2,279M ($3.53B) |
| Aug 7, 2026 | GPU loans | DDTL 5.5 signed at Term SOFR + 5.50%: adds a contract value trap and two sweeps ($2.60B) |
| Sep 22, 2026 | Parent debt | 2.875% converts due 2033: priced September 17, 2026 after the close, pricing release September 18, issued September 22 ($4.20B) |
What CoreWeave owed at June 30, 2026, by instrument, by recourse and by year due.
| Instrument | Principal | Squares | Recourse | Note |
|---|---|---|---|---|
| DDTL 1.0 | $1.30B | 13 | Recourse | |
| DDTL 2.0 | $3.19B | 32 | Recourse | |
| DDTL 2.1 | $3.00B | 30 | Recourse | |
| DDTL 3.0 | $2.21B | 22 | Recourse | |
| DDTL 4.0 | $2.84B | 28 | Non-recourse | |
| DDTL 5.0 | $1.10B | 11 | Recourse | |
| 9.250% notes 2030 | $2.00B | 20 | Recourse | |
| 9.000% notes 2031 | $1.75B | 18 | Recourse | |
| 9.750% notes 2031 | $2.75B | 28 | Recourse | |
| 9.625% notes 2032 | $1.25B | 12 | Recourse | |
| 8.500% EUR notes 2032 | $2.28B | 23 | Recourse | |
| 1.75% converts 2031 | $2.59B | 26 | Recourse | |
| 1.75% converts 2032 | $4.00B | 40 | Recourse | |
| OEM and software financing | $4.22B | 42 | Recourse | OEM financing pays for equipment bought from its makers and is secured by that equipment, $4.8B outstanding. Software license financing covers financed software licenses, $347M outstanding. Source: 10-Q Note 10 ($4.8B OEM, $347M software, across both lines); 10-K (security interest in financed equipment). |
| Magnetar loan | $189M | 2 | Recourse | Magnetar’s $189M is a refundable capacity prepayment from MagAI Ventures with a 12% return, which CoreWeave reports as debt, due January 2029. Source: 10-K p. 118 (refundable $230M prepayment, 12% return, in-substance debt); 10-Q Note 10 ($100M repaid June 2026, due January 2029). |
| Subsidiary OEM and software | $882M | 9 | Non-recourse | Source: 10-Q Note 10 (non-recourse at subsidiaries, August 2026 to August 2028). |
| Total | $35.55B | 356 | $31.8B / $3.7B |
| Principal due (10-Q schedule) | Principal | Squares |
|---|---|---|
| Rest of 2026 | $4.41B | 44 |
| 2027 | $6.18B | 62 |
| 2028 | $4.42B | 44 |
| 2029 | $2.42B | 25 |
| 2030 | $3.22B | 32 |
| 2031 and later | $14.90B | 149 |
| Total | $35.55B | 356 |
An illustrative example. One dollar of customer payment moves down the payment order of DDTL 2.0 and DDTL 5.5, one tier at a time.
CoreWeave, Inc. issues the notes and converts and borrows under the revolver. Three subsidiaries guarantee the revolver, the converts and the notes issued since July 2025. Each GPU loan sits in a special-purpose borrower, or SPV, that holds its own GPUs and customer contracts.
Issues the notes and converts; borrows under the revolver
CoreWeave, Inc.
Guaranteed by:
The 2030 notes name only CoreWeave Cash Management, as filed. CoreWeave Debt Holdco I also owns the holding companies for DDTL 3.0, 4.0, 5.0 and 5.5.
Senior notes
Convertible notes
Bank and other
CoreWeave, Inc. pledges directly
No holding company. CoreWeave, Inc. is the sole member.
DDTL 1.0
CoreWeave Compute Acquisition Co. II
$1.30B
Customer: Redacted (two MSAs)
Full payment guarantee
CoreWeave, Inc. pledges directly
No holding company. CoreWeave, Inc. is the sole member.
DDTL 2.0 and 2.1
CoreWeave Compute Acquisition Co. IV
$6.19B
2.0 $3,190M · 2.1 $3,000M
Customer: Microsoft named; OpenAI in 2.1 only; others unfiled
Full payment guarantee
CCAC VII Holdco
under CoreWeave Debt Holdco I
Pledges Co. VII only. Co. V is held directly by CoreWeave, Inc., and its equity is not pledged.
DDTL 3.0
CoreWeave Compute Acquisition Co. VII
Co-borrower Co. V, outside the guarantee and the equity pledge
$2.21B
Customer: OpenAI
Guarantee covers one of two borrowers
Guarantee can fall away from Apr 30, 2027
CCAC VIII Holdco
under CoreWeave Debt Holdco I
DDTL 4.0
CoreWeave Compute Acquisition Co. VIII
$2.84B
Customer: Redacted (one MSA)
Bad-acts guarantee only
Non-recourse
CW Financing DDTL V Holdco
under CoreWeave Debt Holdco I
DDTL 5.0
CoreWeave Financing DDTL V
$1.10B
Customer: Redacted (two MSAs)
Full payment guarantee
CW Financing DDTL V-V Holdco
under CoreWeave Debt Holdco I
DDTL 5.5
CoreWeave Financing DDTL V-V
$1.20B
Drawn after June 30; not in the June 30 table
Customer: Redacted (five MSAs)
Full payment guarantee
No 10-Q has classified it yet. Recourse is our reading of its guarantee.
Principal from the debt table in CoreWeave's 10-Q for June 30, 2026. Before unamortized discount, recourse principal was $31.8 billion and non-recourse $3.7 billion. Of the non-recourse total, $882 million is subsidiary equipment and software financing. After June 30, CoreWeave drew $1.2 billion on the revolver and sold $4.2 billion of 2.875% converts due 2033.
The parent guarantees full payment on four of the six GPU loans: DDTL 1.0, 2.0, 5.0 and 5.5. On DDTL 3.0 it guarantees one of the two borrowers. The 10-Q lists the first five as recourse, $10.8 billion of principal at June 30. CoreWeave drew $1.2 billion on DDTL 5.5 after the quarter.
The 10-K and 10-Q call every GPU loan but DDTL 4.0 "unconditionally guaranteed." The DDTL 3.0 guarantee itself covers only the initial borrower, and the 8-K for that loan says the same.
The guarantees come in three forms. On DDTL 1.0 and 2.0, CoreWeave, Inc. guarantees the loan and pledges the borrower's equity itself. No holding company sits between them. These guarantees also limit the parent's own dividends and buybacks. CoreWeave amended both twice in late 2025. The November amendments permit payments on a separate convertible promissory note, capped at $225 million. The December amendments cover the 2031 converts and their capped calls.
On DDTL 3.0, 5.0 and 5.5, a holding company pledges the borrower's equity and the parent guarantees payment. CoreWeave Debt Holdco I, one of the bond guarantors, owns each of these holding companies and DDTL 4.0's. These guarantees carry parent covenants: net leverage at or below 6.00 times and at least $1 billion of contracted revenue. In DDTL 5.0 and 5.5 they apply only while the revolver requires them. In DDTL 3.0 they stand alone, with leverage defined as in the revolver.
DDTL 3.0 has two borrowers, and the guarantee covers only one of them. The other, CoreWeave Compute Acquisition Co. V, holds the OpenAI contract. CoreWeave, Inc. owns it directly, and no filed document pledges its equity. From April 30, 2027, the guarantee can fall away if OpenAI gets investment-grade ratings from S&P and Moody's and other conditions are met.

DDTL 4.0, an $8.5 billion facility, gives its lenders no payment guarantee. Its borrower's landlord holds a contingent one (section 07). To the lenders, the parent answers only for losses from five acts. They are fraud, willful misconduct that causes material physical damage, misappropriation of collateral, a voluntary bankruptcy filing, and consent to an involuntary case or a receiver. The acts of the parent, Debt Holdco I, the holding company, the borrower or its subsidiaries count. The guarantee covers losses and excludes claims under the loan documents. The 10-Q lists the loan as non-recourse.
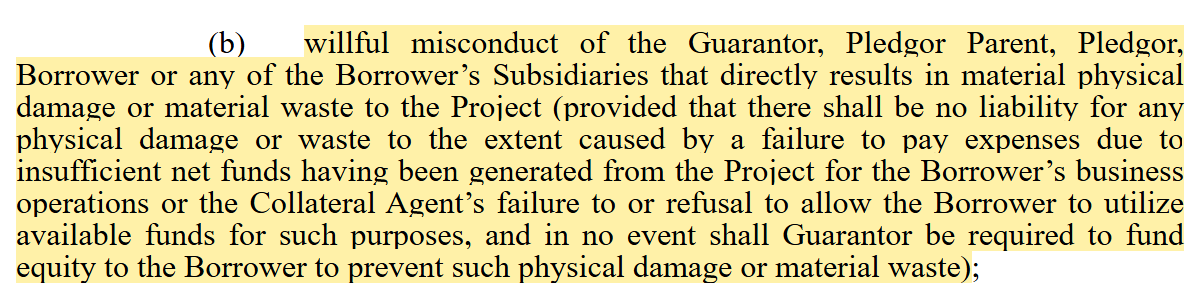
No guarantee in the set obliges the parent to put in equity, cover cost overruns or complete a project. None releases the parent when the customer accepts the GPUs. Apart from the DDTL 3.0 fallaway, each ends only when the loan is paid or the lenders vote to release it.
The revolver, the converts and the notes issued since July 2025 have one guarantor group: CoreWeave Cash Management, CoreWeave Debt Holdco I and Weights and Biases. No GPU borrower guarantees them. The 2030 notes are the exception as filed. Only CoreWeave Cash Management signed that indenture. It requires the other two to join once they guarantee the revolver, which they did in November 2025. No joinder is filed.
The indentures treat each GPU borrower as a restricted subsidiary. Its debt and earnings count in the bond ratios. Its assets can secure its own loans without securing the bonds.

The 10-Q states what the SPVs pledge. The SPV facilities other than DDTL 4.0 were secured by $20.8 billion of assets at June 30. DDTL 4.0's borrower held another $3.5 billion.
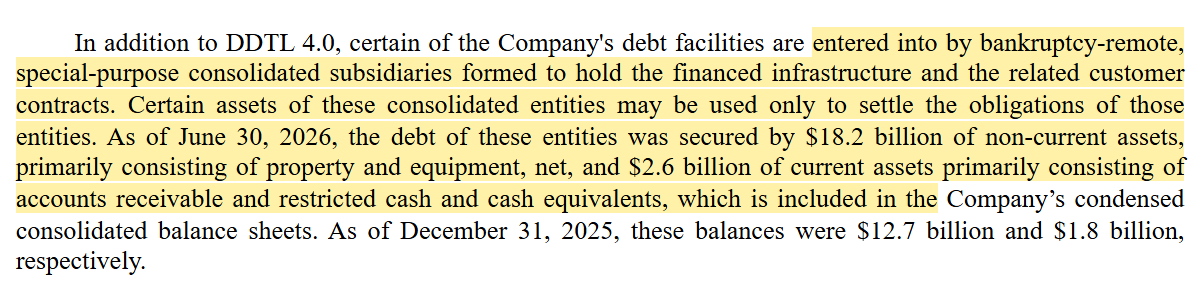
CoreWeave's net property and equipment was $46.7 billion. By our subtraction, about $25 billion of it sits outside the disclosed SPV pools. It is not all free of liens. The 10-K says OEM lenders hold security in the equipment they financed. OEM financing was $4.8 billion at June 30, across the recourse and non-recourse lines. The $189 million Magnetar loan is a refundable prepayment that the 10-Q carries as debt. The revolver is secured under a security agreement that is not filed. Its collateral excludes the equity of the SPVs.
CoreWeave files no parent-only financial statements and no guarantor financial summary. Its notes were sold in private offerings, and the SEC rule for a guarantor summary covers registered debt. The filings give no list of unpledged assets.
At each GPU borrower
At CoreWeave, Inc. and its guarantors
On our reading, the bonds reach two things. One is the assets of the parent and its guarantors, after the secured revolver and OEM lenders. The other is the group's equity in each SPV, after that SPV's lenders are paid. That equity is pledged to the SPV's lenders. For DDTL 3.0, 4.0, 5.0 and 5.5, it sits in holding companies under Debt Holdco I, a bond guarantor. Unsecured lease and trade claims against the parent rank with the bonds. Operating lease liabilities were $16.3 billion at June 30. Leases signed by a GPU borrower reach the parent only through a springing guaranty (section 07).
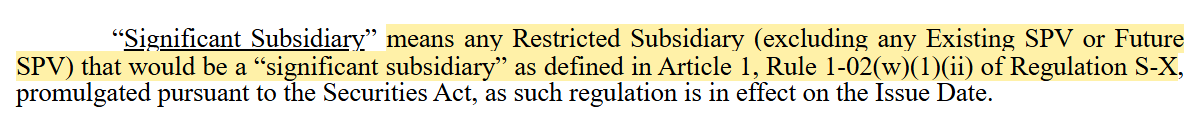
The default terms leave the GPU borrowers out. The bankruptcy default covers the company and guarantors that are significant subsidiaries. The GPU borrowers are not guarantors, and an SPV cannot be a "Significant Subsidiary." On our reading of the 2032 indenture, an SPV's own bankruptcy is therefore not directly a bond event of default.
A default on a loan the parent guarantees can reach the senior notes. Their cross-default covers debt the parent guarantees, above the greater of $200 million and 5% of EBITDA. It applies only on acceleration or nonpayment at final maturity. The converts' cross-default has no such limb. It covers only borrowed money of the company and its significant subsidiaries.
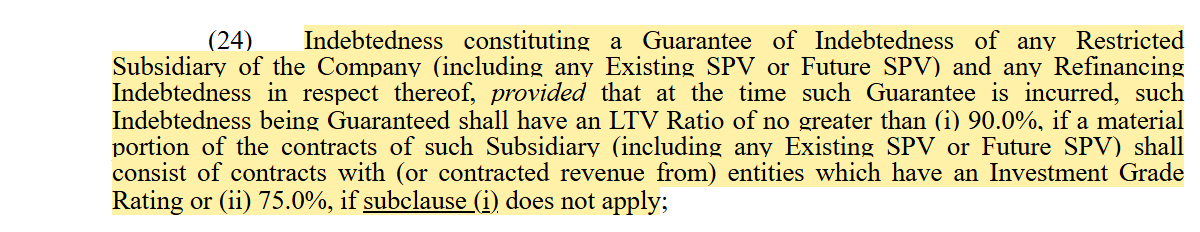
The indentures let the parent guarantee more SPV debt with no dollar cap. Each new guarantee must meet a loan-to-value test. The limit is 90% where a material portion of the SPV's contracts are with investment-grade customers, and 75% otherwise. Value is measured by the company in good faith. Guarantees tied to the OpenAI contract have a $7.0 billion cap.
The revolver sets its own limit on value moving into the SPVs. It applies unless CoreWeave and its guarantors hold $2.5 billion of liquidity, counting cash and undrawn revolver commitments. Below that level, liquidity plus the greater of depreciated equipment or contract backlog must exceed secured debt plus revolver commitments. Restricted cash does not count toward that liquidity.
A default on the parent's notes or converts does not by itself put DDTL 1.0, 2.0, 3.0, 5.0 or 5.5 in default. Those loans react to a shorter list of parent events. The list covers bankruptcy, large unpaid judgments and a change of control. It also covers breaches of the parent guarantee and acceleration of a bank revolver or working-capital line above a set threshold. DDTL 1.0 and 2.0 add the 2021 Magnetar note agreement. (DDTL 1.0 and 2.0, Sec. 7.01; DDTL 3.0, 5.0 and 5.5 guarantees, "Guarantor Trigger Event.")
In DDTL 3.0, these events reach only the initial borrower's side. In DDTL 4.0, no parent event is a loan default. A parent bankruptcy traps the borrower's cash and blocks new draws. (DDTL 3.0, Sec. 7.01(o); DDTL 4.0, "Cash Trap Event" and Sec. 4.02(i).)
The path also runs the other way, through the revolver. Since its November 2025 amendment, the GPU borrowers are restricted subsidiaries under the revolver. A GPU borrower's bankruptcy is then a revolver event of default. So is a default on a GPU loan, DDTL 4.0 included, above the greater of $200 million and 5% of EBITDA. On our reading, a revolver acceleration above that same threshold would reach the cross-acceleration terms of the notes and converts. CoreWeave drew $1.2 billion on the revolver in August 2026. (Revolver Amendment No. 4, events of default; 2032 indenture, Sec. 6.1(a)(4).)
Each GPU borrower is a limited-purpose company with at least one independent manager. The 10-Q calls these subsidiaries bankruptcy-remote. On our reading, a CoreWeave, Inc. filing does not make a GPU borrower a debtor in that case. The borrower would have to file its own petition. (Each credit agreement, Sec. 5.13.)
For DDTL 1.0, 2.0, 5.0 and 5.5, a parent bankruptcy is a loan default. Lenders can then accelerate and enforce against the borrower's GPUs, contracts and accounts. Their guarantee claim becomes a claim in CoreWeave, Inc.'s own case. DDTL 3.0 works the same way for its initial borrower only.
In DDTL 4.0, a parent bankruptcy traps the borrower's cash and blocks new draws. It is not a loan default. The limited guarantee covers losses directly caused by a voluntary parent filing. It excludes claims under the loan documents themselves. (DDTL 4.0 limited guarantee, Schedule 1(d).)
Operations differ across the loans too. In DDTL 1.0, the parent held the data center leases and served the borrower under a services agreement (not publicly filed). From DDTL 3.0 on, the borrower pays its own operating costs first. On our reading, the later borrowers depend less on the parent to keep their GPUs running.
CoreWeave's facilities are on the CoreWeave debt page. How a single loan holds its collateral is in The GPU SPV. How Fitch rated DDTL 5.5 is in A GPU Lease Rate Enters the Rating Case.
The bonds allow SPV lenders to block dividends to the parent. Each SPV loan sets the tests that cash must pass first.
DDTL 1.0 · cash goes up quarterly
DDTL 2.0 and 2.1 · cash goes up quarterly
Spare cash in one tranche’s reserve must cover a shortfall in the other’s fees, interest and principal. The 10-K says $500M sat in escrow for this loan from the March 2025 IPO until April 2025. No filed loan document sets that term.
DDTL 3.0 · cash goes up monthly
An agreement among the lenders, OpenAI and Dell Financial Services can override this order after a triggering event. That agreement is not filed.
DDTL 4.0 · cash goes up monthly
DDTL 5.0 · cash goes up monthly
DDTL 5.5 · cash goes up monthly, after the draw period
If a customer contract expires without renewal or replacement, part of the loan must be repaid.
The order of payments changed across the loans. DDTL 1.0 through 2.1 pay the lenders first, on quarterly dates. Fees, interest and principal come before the borrower’s operating costs, which cover only contracts assigned to the borrower. From DDTL 3.0 on, operating costs come first and interest is paid monthly. DDTL 3.0 caps those costs at $50 million a month.
In DDTL 1.0, the parent held the data center leases and agreed to try to assign them to the borrower. It served the borrower under a services agreement (not publicly filed). Fees the borrower pays the parent count as restricted payments, so they come after the lenders. DDTL 2.0 added a test in December 2024: operating costs may be paid only if cash left covers the next quarter's interest and principal. (DDTL 1.0, Sec. 6.06 and parent guarantee Sec. 5.16; DDTL 2.0 Second Amendment, Sec. 5.25.)
With a full parent guarantee behind them, lenders did not need the borrower to cover its own running costs. From DDTL 3.0 on, guarantees narrow, and lenders rely on the borrower's own cash. Paying power and space first keeps the GPUs running and the contracts paying, even if the parent fails. DDTL 3.0's guarantee can fall away only if, among other conditions, the parent signs a securitization-style management agreement and a performance guaranty. In DDTL 4.0, a parent bankruptcy traps cash and is not a loan default. The filings set out each of these terms. The reason for the change is our reading.
In DDTL 1.0 through 2.1, customer cash lands in a trust account in the collateral agent's name. From DDTL 3.0 on, the borrower runs the account, and the agent's control springs only on enforcement.
Every loan has the same core tests. There must be no default and no cash shortfall. Scheduled principal must be paid, and the liquidity requirement must be met. Cash then moves up monthly or quarterly.
Payments outside the routine path need a cash cushion 15% above the next payment. They also need a set share of deployed servers invoiced and paid: 99% in DDTL 2.0 and 3.0, with the level redacted in the others.
DDTL 1.0 has no cash trap. There, the termination of a customer contract, or a default under it, is itself an event of default. The borrower has 90 days to replace the contract on similar terms. An event of default blocks payouts and lets the lenders accelerate. (DDTL 1.0, Sec. 7.01(m) and 7.02.)
From DDTL 3.0 on, a material breach of a customer contract traps cash in the borrower if the breach gives a right to terminate. In DDTL 3.0 and 5.5 that right belongs to the customer, so the breach is usually CoreWeave's own. In DDTL 4.0 and 5.0, a breach by either side counts. DDTL 3.0 also traps after three straight months of OpenAI non-payment. DDTL 4.0 also traps on a CoreWeave, Inc. bankruptcy. DDTL 5.5 also traps when projected contract value falls below 2.40 times the loan. If its trap runs three straight monthly payment dates, all cash in the loan's collateral accounts repays the loan until the ratio is back above 2.40 times.
DDTL 5.5 makes no distributions until its draw period ends, on December 31, 2026 at the latest. Draw proceeds can still pay the parent's equipment invoices within seven business days, and tax distributions need agent consent. After the draw period, cash moves up only while the loan is at or below $1.3 billion. CoreWeave reported $1.2 billion drawn in its August 10-Q.
Every GPU loan lets draw proceeds pay the parent's invoices for the GPUs it sells the borrower, within seven business days of a draw. DDTL 4.0 has one more route up. New loans drawn against a running site can go straight to the parent. The site must still meet sizing tests, including projected debt service coverage of 1.20 times. Each site gets one such draw, with four at most.
The filings give no figure for the cash the SPVs paid up. Restricted cash across the group was $1.38 billion at June 30. The 10-Q says it was primarily bank deposits related to its collateralized loan facility.
CoreWeave signed six GPU loans in three years. The chart shows each margin over SOFR at signing. The table sets the terms side by side.
| DDTL 1.0 | DDTL 2.0 | DDTL 3.0 | DDTL 2.1 | DDTL 4.0 | DDTL 5.0 | DDTL 5.5 | |
|---|---|---|---|---|---|---|---|
| Signed | Jul 2023 | May 2024 | Jul 2025 | Sep 2025 | Mar 2026 | May 2026 | Aug 2026 |
| Commitment | $2.3B | $7.6B | $2.6B | $3.0B | $8.5B | $3.1B | $2.6B |
| Customer | Redacted | Microsoft and unfiled others | OpenAI | Microsoft and OpenAI | Redacted | Redacted | Redacted |
| Over SOFR | 9.62% (8.75% at signing) | 6.00% to 13.00% by customer grade | 4.00% | 4.25% | 2.25% floating; fixed tranche over Treasuries | 4.50% | 5.50% |
| Pays | Quarterly | Quarterly | Monthly | Quarterly | Monthly | Monthly | Monthly |
| Parent guarantee | Full | Full | One of two borrowers | Full | Bad acts only | Full | Full |
| Equity pledged by | CoreWeave, Inc. directly | CoreWeave, Inc. directly | A holding company under Debt Holdco I, for Co. VII only | CoreWeave, Inc. directly | A holding company under Debt Holdco I | A holding company under Debt Holdco I | A holding company under Debt Holdco I |
| Paid first | Lenders | Lenders | Operating costs, up to $50M a month | Lenders | Operating costs | Operating costs | Operating costs |
| Liquidity reserve | Funded reserve outside the waterfall: 4.0% of loans, $25M to $56.25M | Funded reserve outside the waterfall: 1.0% of loans, at least $25M | Funded ahead of principal | Funded reserve outside the waterfall: 1.0% of loans, at least $10M | Funded after principal, plus a power reserve | Funded after principal | Funded after principal; $112.5M floor, then 10% of loans |
| Coverage test | Loan sized to contract cash flow and depreciated GPU cost | 1.40x contract coverage | 0.85x contract realization; 1.40x debt service from Oct 2027 | 1.40x contract coverage | 1.15x debt service; 1.20x projected for sizing | 1.35x debt service | 1.35x debt service |
| Cash trap | None; losing a customer contract is a default | None | Breach letting OpenAI terminate, or 3 months unpaid | None | Breach letting either side terminate, or parent bankruptcy | Breach letting either side terminate | Unwaived breach letting the customer terminate, or contract value below 2.40x |
| Sweep | None | None | None | None | None | None | After 3 months trapped; excess cash to $1.3B |
| Hedging required | None | None | Swaps or caps on at least 75% of floating loans, within 45 days of each draw; caps at or below 4.50% | None | Swaps on at least 95% of floating loans after the draw period; power price hedges at two sites | Swaps on at least 95% of loans after the draw period | Swaps on at least 95% of loans after the draw period |
| Prepayment premium | Make-whole plus 1% for three years after the draw period, then 1% for a year | Make-whole to 30 months after the draw period | None; breakage costs only | Make-whole to 30 months after the draw period | Make-whole to maturity | Make-whole in year 1, 2% in year 2, 1% in year 3 | Make-whole, 2%, 1% by year; first $260M of optional prepayments free |
| Guarantee ends | Repayment | Repayment | Repayment, or from Apr 2027 if OpenAI is rated investment grade and other conditions are met | Repayment | Repayment | Repayment | Repayment |
| Maturity | Mar 2028 | Aug 2030 | Aug 2030 | Mar 2031 | Mar 2032 | Nov 2031 | Sep 2031 |
DDTL 1.0 priced at SOFR plus 8.75% in July 2023. An amendment in May 2024 raised the margin to 9.62%.
DDTL 2.0 priced each loan by the grade of the customer behind it. Loans for two named Microsoft order forms pay 6.00% over SOFR. Loans for other investment-grade customers pay 6.50%, and the rest pay 13.00%.
Later loans carry one margin. DDTL 3.0, for OpenAI, pays 4.00%. The 2.1 tranche, for Microsoft and OpenAI, pays 4.25%.
DDTL 4.0 has the largest commitment signed in one agreement, $8.5 billion, and the lowest floating margin, 2.25%. It is also the only one with no payment guarantee. Its fixed loans pay 2.00% over a blend of Treasury yields set at each fixed draw. The closing press release put the fixed rate at about 5.9%. MUFG's fixed loans pay SOFR plus 2.25% instead. Its customer is redacted.
DDTL 5.0 and 5.5 pay 4.50% and 5.50%. Their customers are redacted: two contracts behind 5.0 and five behind 5.5.
The structure changed too. Each loan from DDTL 3.0 on has a holding company that pledges the borrower, and a breach of the customer contract can trap cash. DDTL 5.5 adds a test on contract value and two sweeps.
The 2.1 tranche sits inside the DDTL 2.0 agreement, with the same borrower and guarantee. It keeps DDTL 2.0's payment order, quarterly cycle and 1.40x coverage test. It has its own collateral pool, accounts, waterfall and covenants. Its advance rates are 90% for Microsoft and 75% for OpenAI, and it set a $2.4 billion minimum draw. A full prepayment of 2.0 forces a full prepayment of 2.1. A partial one forces the same share. (DDTL 2.0 Fifth Amendment, Sec. 2.09(d), 2.23 and 6.13.)
Repayments on DDTL 1.0, 2.0 and 2.1 are resized each period to contract cash flow, coverage or depreciated GPU cost. DDTL 3.0 repays on a fixed schedule. DDTL 4.0, 5.0 and 5.5 repay on schedules that are not filed. DDTL 4.0 also resizes for late sites and at the end of its draw period.
DDTL 2.0 also carries a waiver. In December 2024, the borrower told its lenders that five draws, from October 11 to December 31, 2024, had overstated the borrowing base. Loan proceeds had bought GPU servers for CoreWeave entities in Spain, the U.K. and Sweden. Blackstone funds, signing as the required lenders, waived those defaults. The same amendment let the borrower own subsidiaries and made the three foreign entities obligors under the loan. (Limited Waiver and Second Amendment, Sec. 2(b) and Exhibit A.)
Coupons on the parent’s notes and converts come to about $1.1 billion from October 2026 to September 2027. Principal due is larger, but the filings give it only by year.
| Quarter | Date | Instrument | Due |
|---|---|---|---|
| Oct–Dec 2026 | Oct 1 | 9.750% notes 2031, short first coupon | $124M |
| Oct–Dec 2026 | Oct 1 | 1.75% converts 2032, short first coupon | $32M |
| Oct–Dec 2026 | Dec 1 | 9.250% notes 2030 | $93M |
| Oct–Dec 2026 | Dec 1 | 1.75% converts 2031 | $23M |
| Jan–Mar 2027 | Jan 15 | 9.625% notes 2032, long first coupon | $69M |
| Jan–Mar 2027 | Jan 15 | 8.500% EUR notes 2032, long first coupon; €97.75M | $110M |
| Jan–Mar 2027 | Feb 1 | 9.000% notes 2031 | $79M |
| Apr–Jun 2027 | Apr 1 | 9.750% notes 2031 | $134M |
| Apr–Jun 2027 | Apr 1 | 1.75% converts 2032 | $35M |
| Apr–Jun 2027 | Apr 1 | 2.875% converts 2033, long first coupon | $63M |
| Apr–Jun 2027 | Jun 1 | 9.250% notes 2030 | $93M |
| Apr–Jun 2027 | Jun 1 | 1.75% converts 2031 | $23M |
| Jul–Sep 2027 | Jul 15 | 9.625% notes 2032 | $60M |
| Jul–Sep 2027 | Jul 15 | 8.500% EUR notes 2032, €85.0M | $95M |
| Jul–Sep 2027 | Aug 1 | 9.000% notes 2031 | $79M |
| Estimate input | Balance | Rate | Per quarter |
|---|---|---|---|
| DDTL 1.0 | $1300M | 15% | $49M |
| DDTL 2.0 | $3190M | 11% | $88M |
| DDTL 2.1 | $3000M | 9% | $68M |
| DDTL 3.0 | $2215M | 9% | $50M |
| DDTL 4.0 | $2837M | 7% | $50M |
| DDTL 5.0 | $1101M | 9% | $25M |
| DDTL 5.5, proxy: overnight SOFR + 5.50%, fees left out | $1200M | 9.39% | $28M |
| Revolver, 10-Q rate; likely above its cash cost | $1200M | 7% | $21M |
| OEM and software, recourse | $4220M | 11% | $116M |
| OEM and software, subsidiaries | $882M | 9% | $20M |
| Magnetar loan | $189M | 12% | $6M |
The heaviest quarter for coupons is April to June 2027. Five coupons fall due, including the first on the 2033 converts.
Our estimate adds about $356 million a quarter of interest on the GPU loans. Interest on the revolver, OEM and other financing adds about $163 million. Both rest on the 10-Q’s effective rates, which appear to include fees and discount. The DDTL 5.5 line is a proxy: overnight SOFR plus its margin, with fees left out. The revolver line likely runs high. Its cash rate is Term SOFR plus 1.75%, and its 10-Q rate covers a period with nothing drawn.
The 10-Q schedules $4.4 billion of principal for the "remaining portion of 2026," from July, and $6.2 billion for 2027. Part of the 2026 amount fell due before October. The 10-Q does not split these totals by loan or by quarter. They exclude DDTL 5.5, signed after June 30. On our reading of its credit agreement, its repayments start by January 2027.
The $52 billion sometimes quoted for CoreWeave adds its lease liabilities to its debt. This piece maps the $35.6 billion of debt alone. Here is why, and what the leases add.
At June 30, 2026, CoreWeave reported $35.6 billion of total indebtedness. Its balance sheet also carried $16.3 billion of operating lease liabilities and $0.2 billion of finance lease liabilities. Together they come to about $52.1 billion.
We map the $35.6 billion because CoreWeave reports it as its total indebtedness. Its credit agreements, maturity schedule and recourse split all rest on that figure. The 2032 notes indenture and the revolver both leave operating leases, and guarantees of them, out of "Indebtedness." (2032 indenture, Sec. 1.1, "Indebtedness," clause (iii); revolver as amended by Amendment No. 4, same clause.)
Leases have no lender, payment order or collateral package. The two figures also measure different things. Debt is principal owed. The lease liability is future rent discounted to today, at a weighted-average rate of 10%. So the figure below shows leases beside the debt, and no chart on this page adds them together.
June 30, 2026 · same scale · shown side by side, never summed
| Year | Operating leases | Finance leases |
|---|---|---|
| Rest of 2026 | $1,028M | $12M |
| 2027 | $2,116M | $223M |
| 2028 | $2,306M | — |
| 2029 | $2,373M | — |
| 2030 | $2,289M | — |
| Thereafter | $19,023M | — |
| Total rent due, undiscounted | $29,135M | $235M |
| Less imputed interest | ($12,816M) | ($14M) |
| Lease liability on the balance sheet | $16,319M | $221M |
The lease figures rest on three bases. The $16.3 billion covers leases that have started, discounted at CoreWeave's estimated rate for a secured borrowing. Signed leases that have not started add $35.5 billion of future rent, undiscounted. They start between 2026 and 2029 and run seven to 16 years.
The $35.5 billion leaves out leases whose rent depends on the landlord's construction cost. One single-site lease has 393 MW still to deliver, with rent capped at $14.7 billion over 16 years. Other such leases have 355 MW to deliver. The $35.5 billion does include about $1.8 billion owed to special-purpose entities that lease CoreWeave the mechanical, electrical and plumbing systems of one data center. A third-party investor sponsors them, and CoreWeave does not consolidate them.
Operating lease liabilities doubled in six months. They rose from $8.2 billion at December 31, 2025 to $10.1 billion at March 31, 2026 and $16.3 billion at June 30. CoreWeave added $8.4 billion of new lease assets in the first half. The weighted-average remaining term was 12 years at June 30. Of the $29.1 billion of rent still due on started leases, $19.0 billion falls after 2030.
CoreWeave's own filings say only that it leases all of its data centers. They do not name the tenant entity, and CoreWeave has filed none of its data center leases. Landlords' filings name the tenant.
Applied Digital, Galaxy Digital and Core Scientific each name CoreWeave, Inc. as the counterparty. That covers Applied Digital's Polaris Forge 1 campus in Ellendale, North Dakota: Buildings 2, 3 and 4, 400 MW in all. It also covers Galaxy's Helios campus in Texas and Core Scientific's colocation contracts, which Core Scientific accounts for as leases. A September 2026 lease in Niagara Falls, New York, also names CoreWeave, Inc. Where the parent signs, it owes the rent directly.
CoreWeave also posts letters of credit for landlords as a condition of some leases. They totaled $533 million at June 30. They are issued under the revolver and reduce what CoreWeave can draw on it.
Two Polaris Forge 1 leases moved to a GPU borrower on March 30, 2026, the day DDTL 4.0 was signed. CoreWeave, Inc. assigned the Building 3 lease (150 MW) to CoreWeave Compute Acquisition Co. VIII, the DDTL 4.0 borrower. Co. VIII also took a new lease for two of Building 2's four 25 MW data halls.
The parent backs both with a springing guaranty of rent and performance. It springs on a monetary or insolvency default under DDTL 4.0, an acceleration of that loan, or its repayment in full. It also springs if the borrower's customer contract ends, either company becomes insolvent, or the lease goes into default. Once it springs, it covers all rent under those leases, including rent that came due earlier.
For Building 2, CoreWeave, Inc. also owes the landlord a $50 million letter of credit. DDTL 4.0's lenders still have no payment guarantee from the parent. The landlord on that loan's leases holds a contingent one, and a default on DDTL 4.0 can trigger it. (Applied Digital 8-K/A, April 1, 2026, Exhibits 10.1 to 10.3.)
The GPU loans treat data center leases as core contracts. From DDTL 3.0 on, rent is paid before debt service, and the loss of a lease can be a loan default. DDTL 5.0 and 5.5 ask for step-in letters from landlords. (DDTL 3.0, Sec. 7.01(n); DDTL 4.0, 5.0 and 5.5, Sec. 7.01(m); DDTL 5.0 and 5.5, Sec. 5.20(c).)
Sources: CoreWeave Form S-1 exhibits 10.8 to 10.19; 8-K credit agreements and parent guarantees for DDTL 2.0 (Fifth Amendment), 3.0, 3.0 First Amendment, 4.0, 5.0 and 5.5; FY2025 Form 10-K exhibits 10.13, 10.14, 10.18, 10.22, 10.23 and 10.31; FY2025 Form 10-K and Form 10-Q for March 31, 2026 (Note 8, Leases); Applied Digital Form 8-K of June 2, 2025 and Forms 8-K/A of September 3, 2025 and April 1, 2026; Galaxy Digital Form 8-K/A of October 20, 2025, exhibit 10.1; Core Scientific FY2025 Form 10-K; Blockfusion Form S-4/A of September 23, 2026, exhibit 10.51; indentures for the senior notes due 2030, 2031 (both series) and 2032 (USD and EUR) and the converts due 2031, 2032 and 2033; revolver Amendments No. 3 and 4; DDTL 2.0 Fourth Amendment (Q2 2025 Form 10-Q, exhibit 10.8); Form 10-Q for June 30, 2026; NY Fed SOFR and the ECB euro reference rate for October 15, 2026. Quotes and images are reproduced from the filed text. This page is a research publication of CCIR. It is not investment advice, an offer, or a solicitation.